Real Estate/News
Bank of England: lenders report that the availability of mortgage credit and demand for house-purchase lending both "decreased" in the three months to August, with a slight rise in both expected by November
The Q3 Credit Conditions Survey, from lenders' own responses gathered between 17 August and 4 September: secured and unsecured credit availability down, demand for house-purchase and remortgage lending down, credit to small and medium-sized businesses down. On the Bank's scale a "decrease" is a net balance below -10. The Bank: "The results do not necessarily reflect our views on credit conditions."
By Daily Aletheia · Checked against the primary source · 8 October 2026 · 2 min read
The Bank of England's Credit Conditions Survey for 2026 Q3, published on 8 October, is a quarterly poll of "bank and building society lenders". "Lenders were asked to report changes in the three months to end-August 2026 (Q3), relative to the period between March and May, and expected changes in the three months to end-November 2026 (Q4), relative to the period between June and August. The survey was conducted between 17 August and 4 September 2026. Any impact from more recent developments will therefore not be captured."
Supply. "Lenders reported that the availability of secured credit to households decreased in the three months to end-August 2026 (Q3). It was expected to increase slightly over the next three months to end-November 2026 (Q4)". Unsecured credit to households "decreased in Q3 and was expected to increase slightly in Q4". For companies, "credit availability to small businesses and medium-sized businesses decreased and to large businesses was unchanged in Q3".
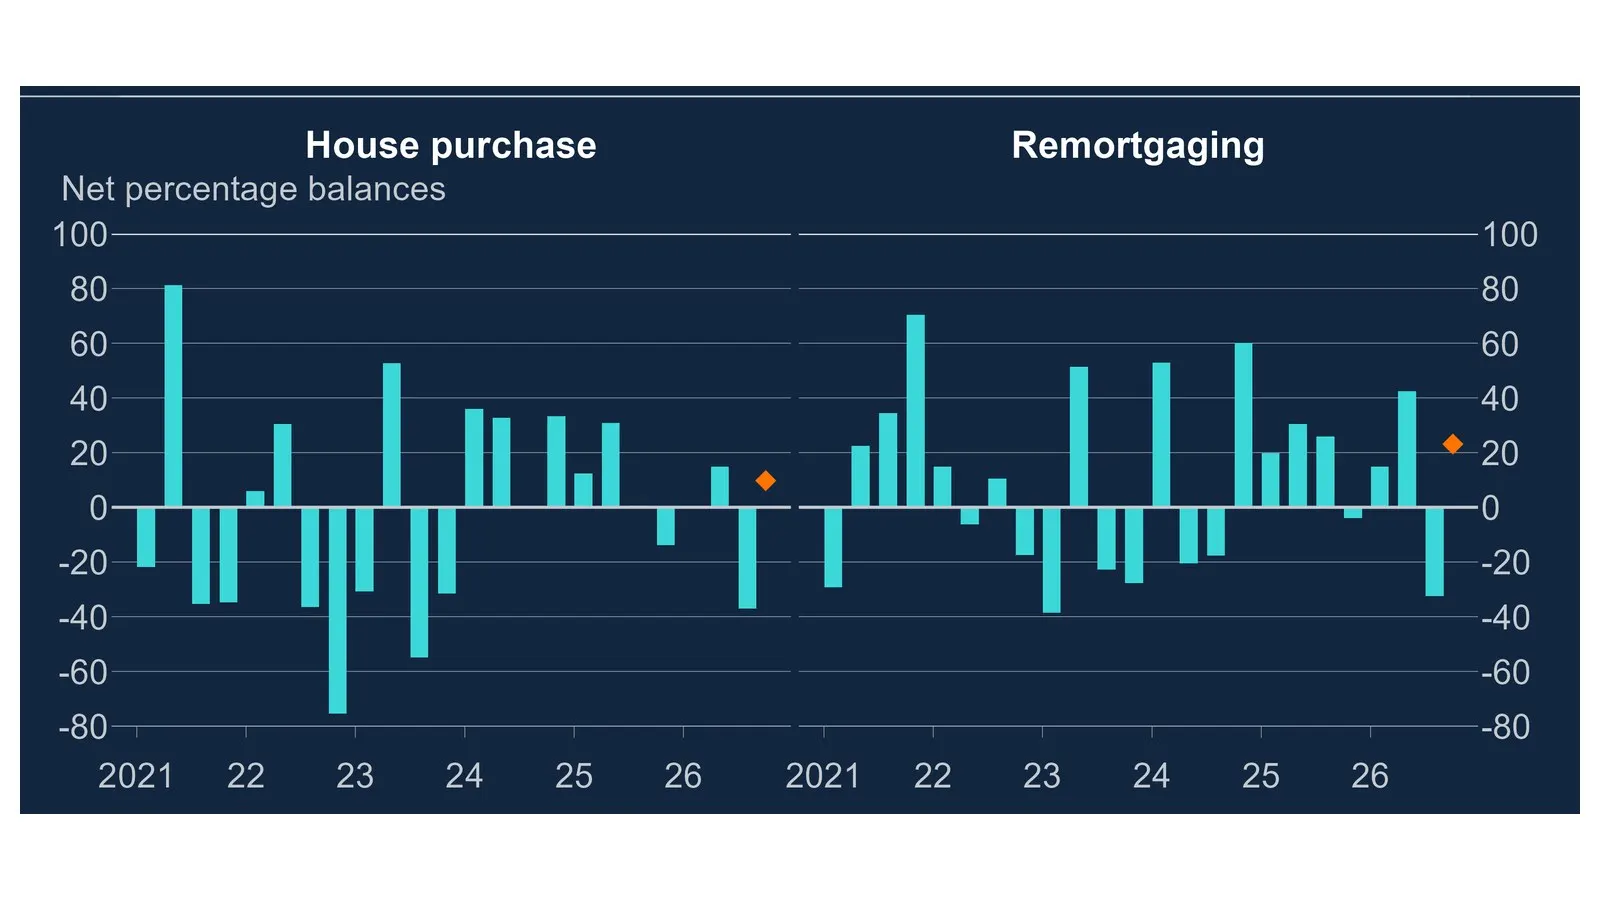
Demand. "Lenders reported that demand for secured lending for house purchase decreased in Q3, and was expected to increase slightly in Q4. Demand for secured lending for remortgaging decreased in Q3, and was expected to increase in Q4". Overall demand for unsecured lending was "unchanged in Q3"; "demand for corporate lending from small businesses and medium-sized businesses decreased".
How to read it. The results are based on "lenders' own responses to the survey, and are reported as net percentage balances. Changes in balances are described as an 'increase' when the balance is greater than 10, as a 'decrease' when less than -10, as a 'slight increase' when between 5 and 10, as a 'slight decrease' when between -5 and -10, and as 'unchanged' when less than 5 in absolute terms." On the Bank's chart of demand for house-purchase lending, the Q3 bar sits around -35 after a reading around +15 in Q2, with the Q4 expectation marked near +10 - a reading of the chart; the balances themselves are in the survey's annex. The Bank's own caveat: "Expectations data can be used as an indicator of the potential direction and magnitude of the change expected in the next quarter, but should not be treated as a realised outturn", and "The results do not necessarily reflect our views on credit conditions." The Q4 survey "will be published on 14 January 2027".